Things you may often hear are: a recession is around the corner, markets are overpriced or the AI sector is about to flop. It’s like the never-ending laundry pile that sits in my house, it never really disappears.
Diana Mousina (AMP Capital)
These days when you read the latest news or open up social media, it’s fairly common to be warned that things are about to get bad. Things you may often hear are: a recession is around the corner, markets are overpriced or the AI sector is about to flop. It’s like the never-ending laundry pile that sits in my house, it never really disappears.
Most of the time, investors can live with a pile of downside risks because the positives outweigh the negatives – the economy is growing, profits are rising and investors are optimistic. And while I don’t want to add to the constant noise and doom and gloom that we are subject to in financial markets, the downside risks to growth and financial markets seem to have increased in recent weeks and it’s becoming harder to ignore.
That doesn’t necessarily mean that a market correction is inevitable. But it does suggest that the ride for investors could become bumpier over the remainder of 2026. This Econosights goes through five reasons why.
The surge in bond yields
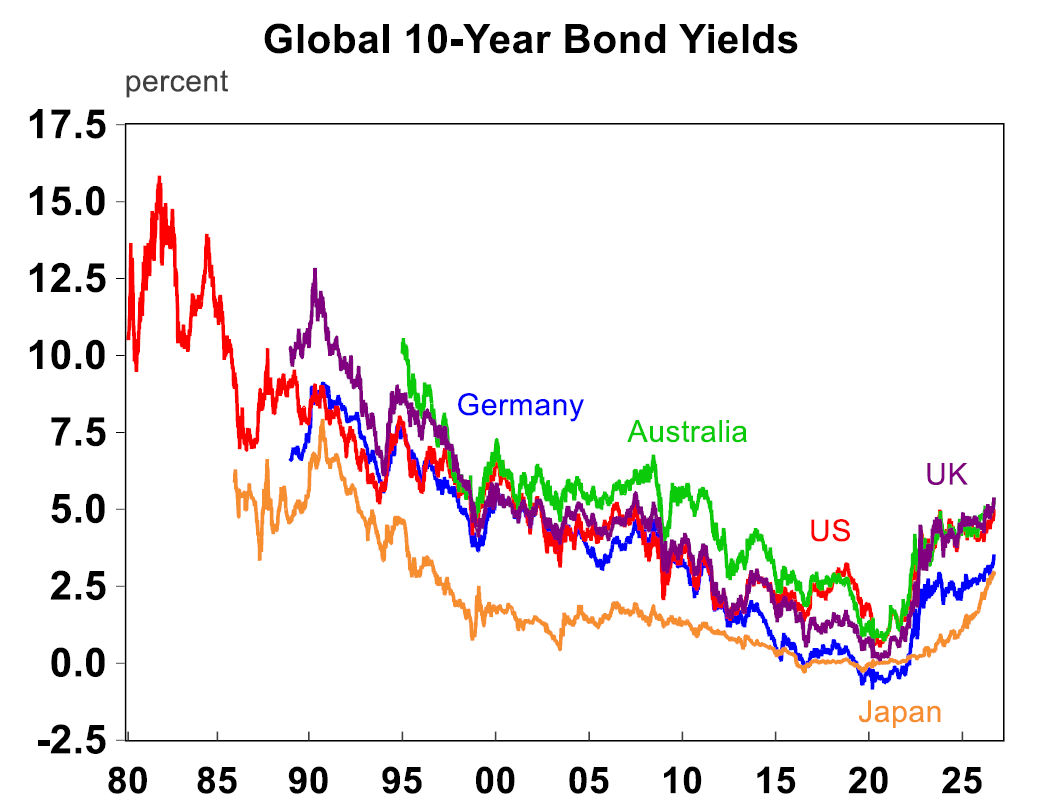
Bond yields are rising around the world. The US 10-year yield touched 5% this week for the first time since 2023 – see the chart below.
Source: Macrobond, AMP
We have written rising bond yields here and here. The rise in yield reflects rising oil prices threatening inflation and leading to more central bank rate hikes, concern about US debt, increased corporate borrowing related to more AI corporate issuance and rising Japanese bond yields for the first time since the early 1990s.
The concern with bond yields rising too far and fast is that it will weigh on sharemarkets. If investors can get a good return for very little risk, they will allocate more to government bonds instead of risking the volatility of investing in growth assets like shares. Right now, strong profit growth is offsetting some of the risks around shares because profit growth is driving prices higher. But if profit growth slows, the relative attractiveness of shares will fall.
Another reason bond yields have moved higher is that investors have started pricing in the risk of further interest rate increases in both Australia and the US, which goes to the second risk.
More rate hikes
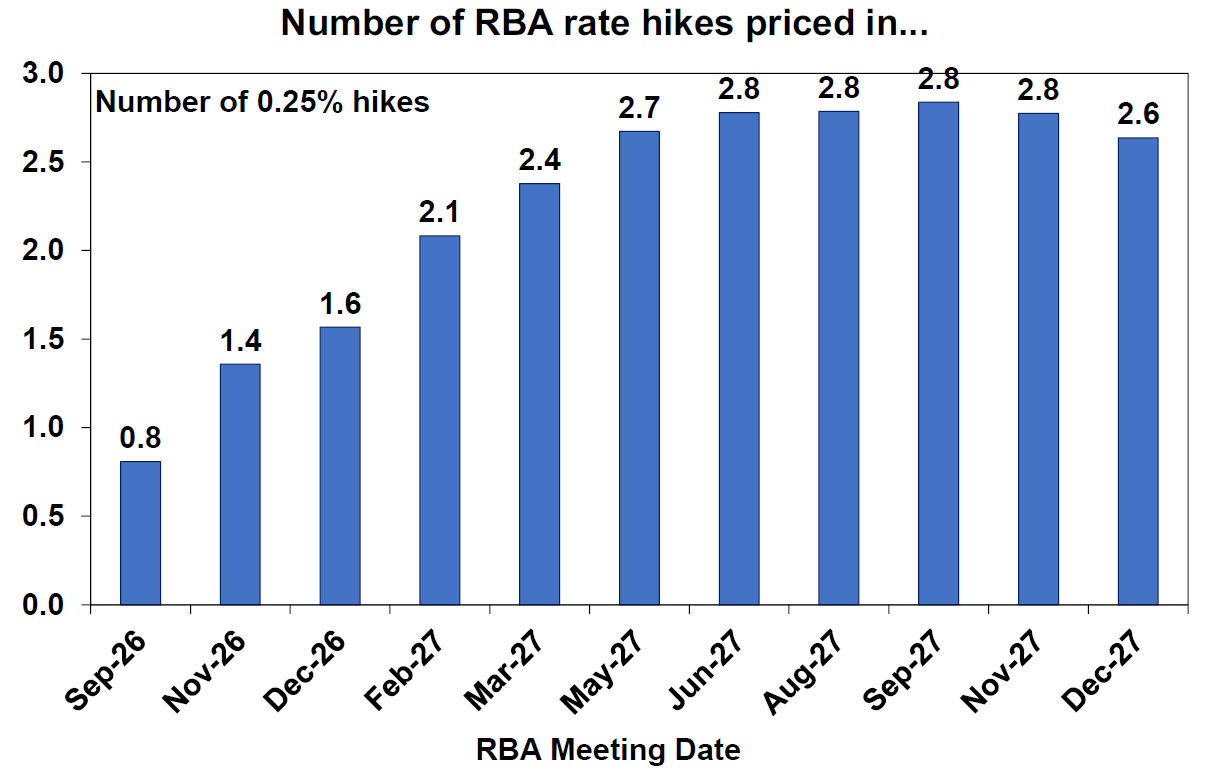
In Australia, the July inflation data significantly increased the chances of another RBA rate hike. Financial markets are now pricing almost three additional rate rises by the end of this year (see chart below). July inflation figures showed trimmed mean at 3.6% over the year to July – way above the RBA inflation goal of 2.5% and also tracking higher than the RBA’s forecasts. As a result, RBA officials have been sounding concerned about the upside inflation risks in recent appearances while downplaying downside growth risks (like the decline in home prices or poor business and consumer confidence surveys). We expect an RBA rate hike later this month, taking the cash rate to a 15-year high of 4.6%.
But we are less convinced that the cash rate needs to go above 5% (which is implied by current market pricing). This seems like over-kill at a time that GDP growth is already slowing, home prices are declining and confidence is falling. Financial market pricing does swing around and is being impacted by the rise in oil price recently, so I think expectations of further rate hikes have moved a little too far.
Source: Bloomberg, AMP
A similar story is playing out in the US. US economic data has had a strong run lately including solid monthly payrolls and firmer inflation readings. Upside inflation risks have also become apparent from another round of tariffs (like those on Canada) and a further rise in oil prices.
Rate hikes are now expected from the US Fed, with markets pricing in two more before the end of the year (see the chart below) and another one in early 2027. Expectations of more rate hikes fuel bond yields and are a key driver of higher yields.
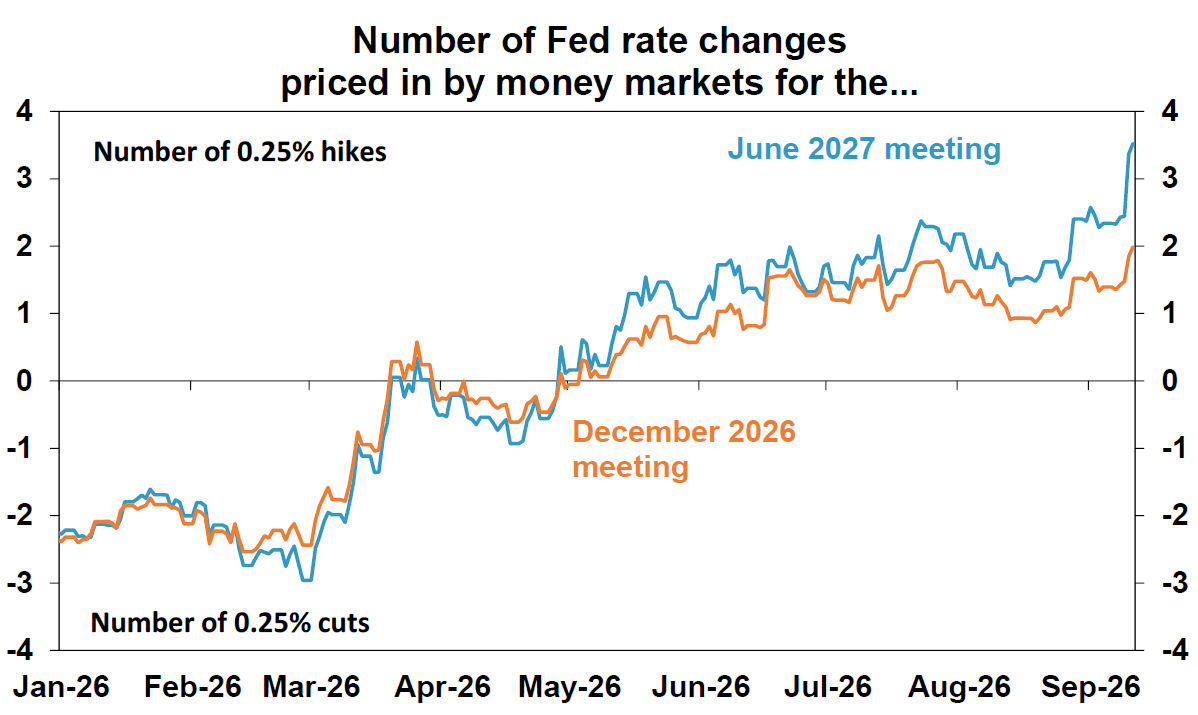
Source Bloomberg, AMP
Rate hikes slow economic growth and can weigh on sharemarkets, particularly if there are a string of rate rises. Higher interest rates increase borrowing costs for households and businesses, which tends to slow consumer spending, business investment and employment growth.
This tends to occur because favourable policies are put through in the first whilst in the second-year, presidents often become more populist, which leads to a slide in approval ratings – and this has happened this time (although the current situation reflects the large increase in gasoline prices since early 2025 due to the Middle East conflict).
Deteriorating oil supplies
The situation in the Middle East has not improved in recent months. Oil prices are back up above $100/barrel – see the chart below.
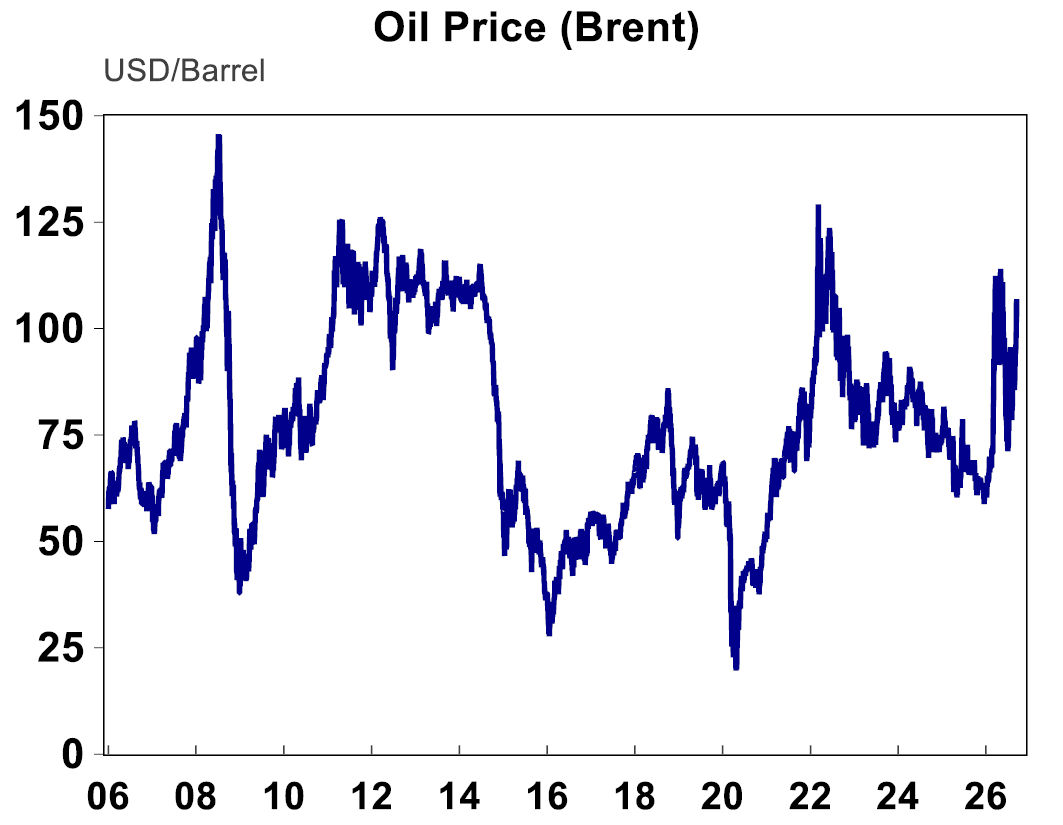
Source: Macrobond, AMP
And the problem is that there do not appear to be any real talks going on between the US and Iran. Some missile attacks have occurred in Iran, on US bases in the Middle East and on ships transiting in the Strait of Hormuz. Now the Iran-backed Houthi rebels have made territorial gains on Yemen’s Red Sea coast which is affecting oil shipping through Bab el-Mandeb Strait which was seeing higher oil flows given the impasse in the Strait of Hormuz.
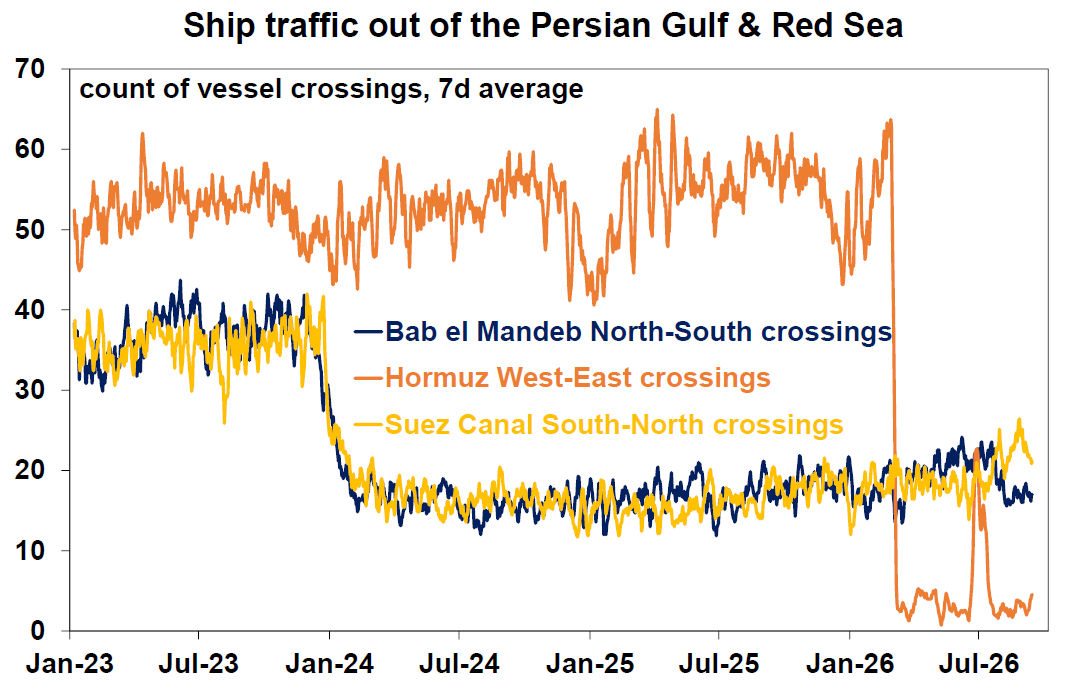
Source: Bloomberg, AMP
Apparently Iran and Oman have made a deal around shipping routes through Hormuz, but nothing is yet confirmed.
Given this impasse, global oil inventory has continued to be drawn down and is now back to its early 2025 levels (see the chart below). This is not yet “crisis” territory. But the longer that oil shipping is impacted then the more that existing inventories are drawn down which increases the risk that oil prices move towards $150/barrel, which would cause a further hit to growth and higher inflation.
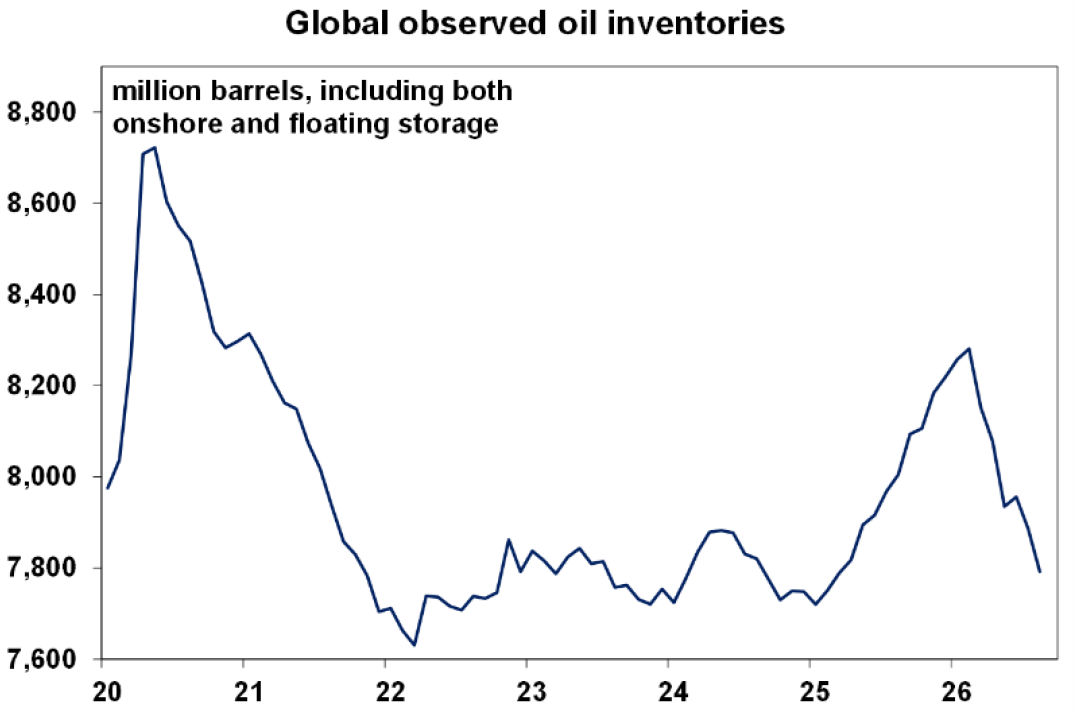
Source: IEA, AMP
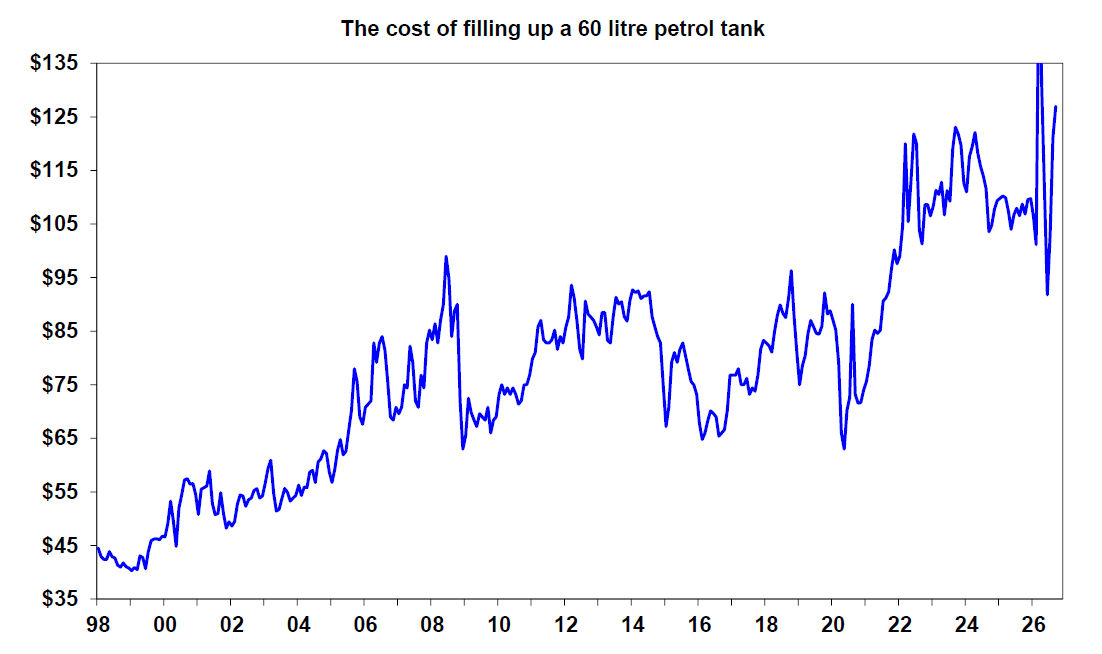
The impact of higher oil prices for households is higher energy costs, mostly through fuel spending but also on utilities because gas. The average Australian household who has a petrol-car is now spending around $127 per week on filling up their car, up $20 a week from pre-war levels.
Source: Bloomberg, AMP
Worsening Australian economic data
Australian economic growth is going to slow in the next 12 months from the effects of interest rate increases, higher inflation hurting purchasing power. We expect GDP growth to moderate to 1.5% by mid 2027, from 2.1% as at June this year.
The concern is that the Australian consumer is starting to buckle more under the weight of the growing negatives of: rising interest rates, elevated inflation eroding purchasing power, falling home prices, disillusion with government, which is why consumer sentiment is still around recession-like lows.
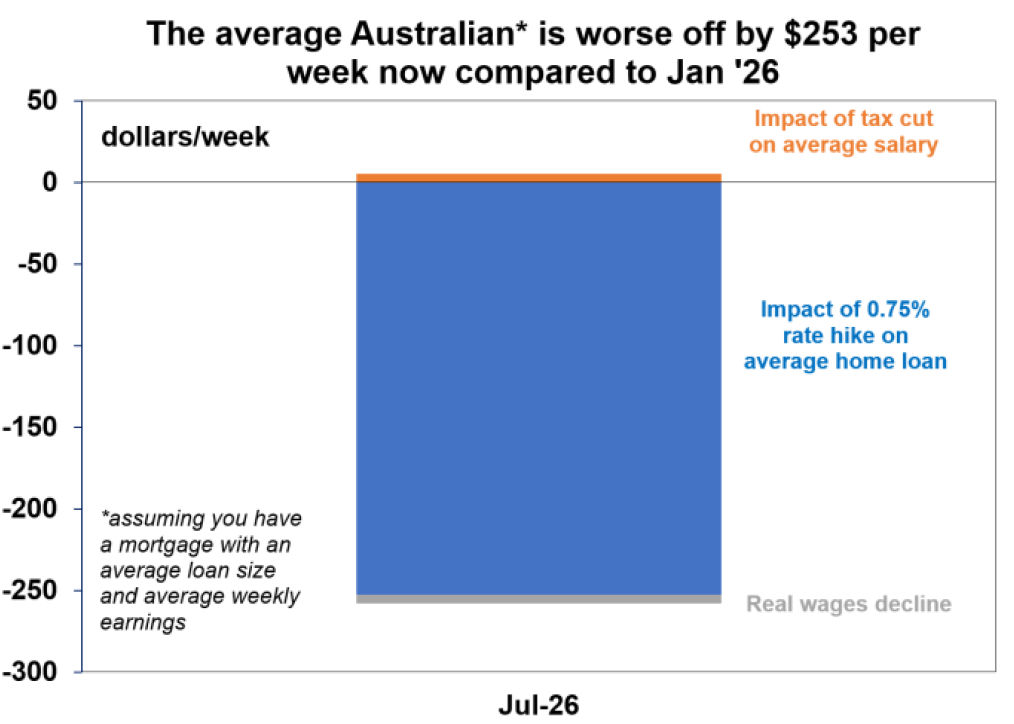
The impact of inflation and changes to wages (which is the real wage change), the small tax cuts from July and the increase to interest rates since February means that an Australian consumer with an average new mortgage (worth around $720,000) is around $253/week worse off compared to January 2026 – which is a sizeable hit.
Source: ABS, RBA, Bloomberg, AMP
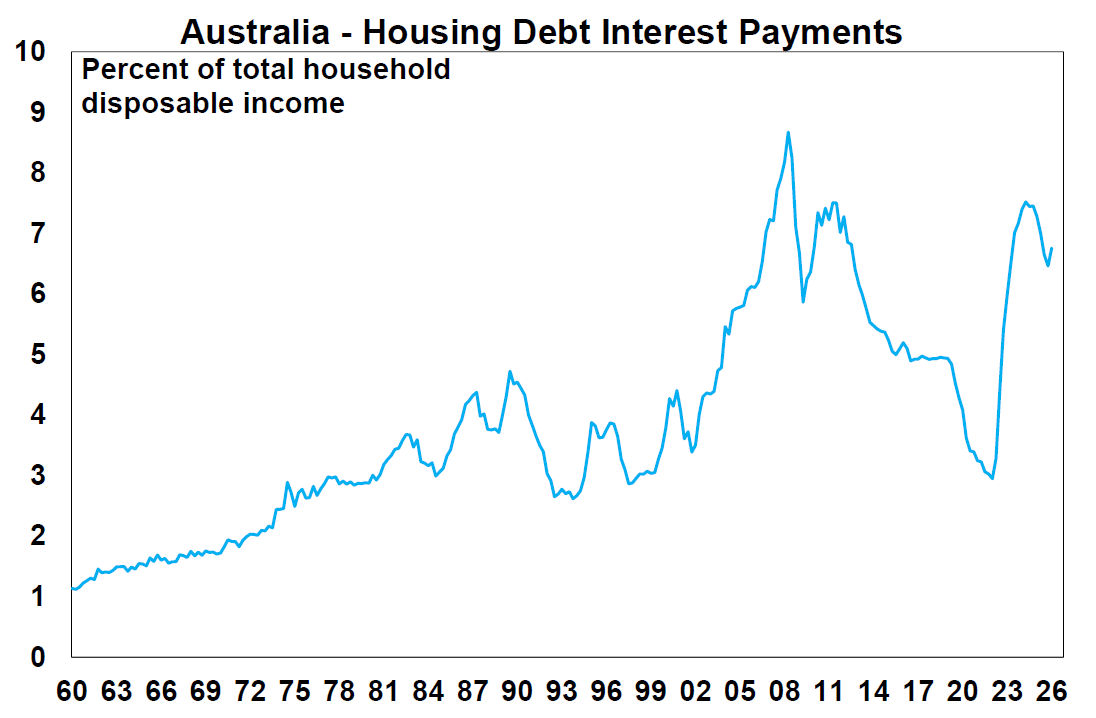
The good news is that mortgage arrears are still low at ~1% of all outstanding loans. But, this will probably rise a little further on further rate rises and some lift to the unemployment rate. The key is that it doesn’t increase too far. Housing interest repayments (as a share of household income) have risen to ~7%, back to ~2011/12 highs (see the chart below) and are likely to get back to their record highs (at over 8%) as interest rate increases take time to flow through to payments and with expected further rate increases, as well as large loans taken out increasing interest expenses. This measure looks at all households, even those without a mortgage so for households with mortgages, the share of income going to housing debt would be even higher.
Source: ABS, BIS, AMP
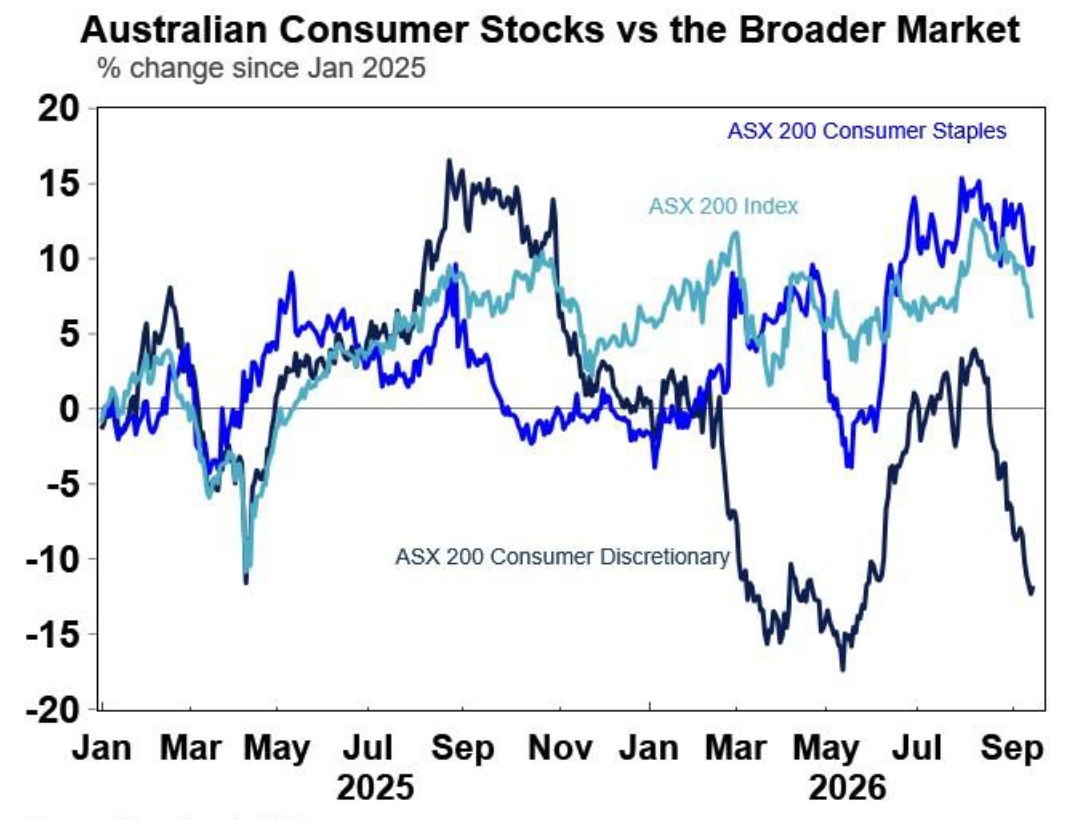
Australian consumer discretionary stocks have not been performing well recently, after the latest reporting season (see the chart below), which could also be a sign that consumer discretionary spending will slow from here.
Source: Macrobond, AMP
Implications for investors
Taken together, these risks suggest that investors are entering a more challenging period as we go into the last quarter of 2026. Higher bond yields, more central bank rate hikes, US political uncertainty and in Australia softer economic data points to a less supportive backdrop for global and domestic sharemarkets in the near-term.
That’s why the next few months could see more volatility and periods of market weakness. US shares are up 10% so far this year while Australian shares had a recent tumble and are now basically flat since the start of the year. Share returns could be softer heading into the end of the year and we expect Australian shares to underperform.
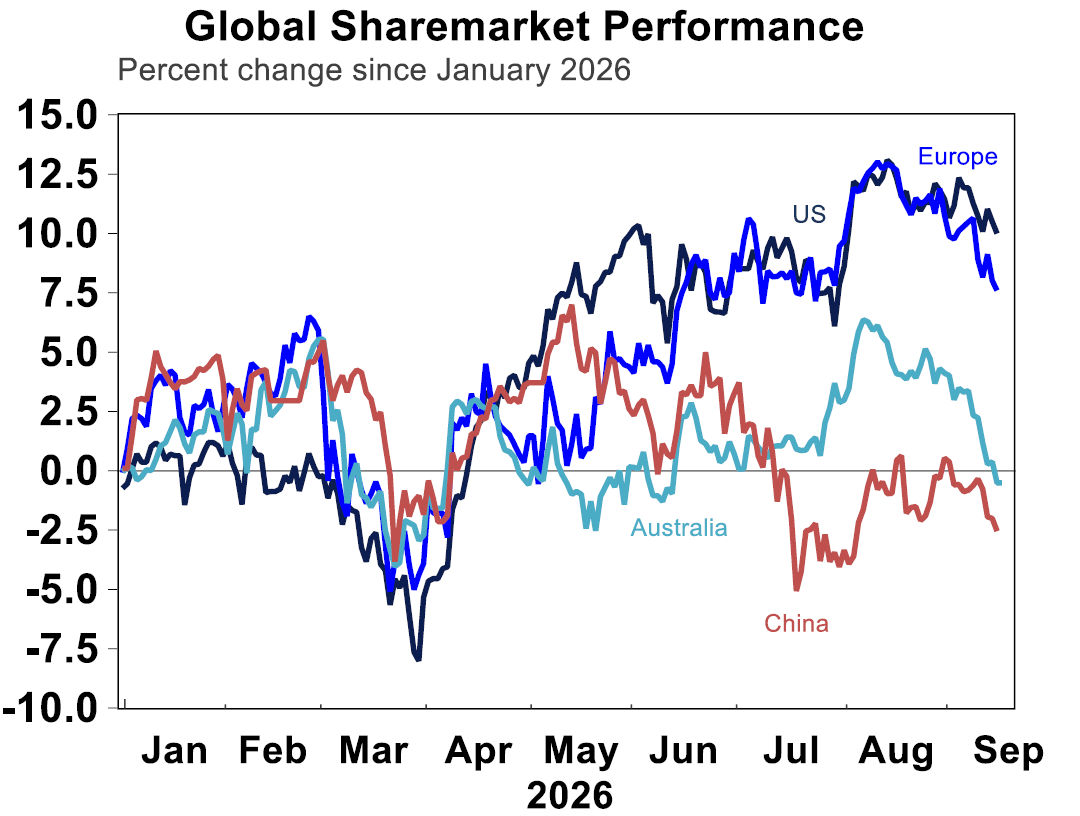
Source: Macrobond, AMP
However, on a longer-term horizon over the next 12 months we are still positive around the outlook thanks to profit growth still holding up, particularly in the tech sector, okay economic growth and no signs of a serious economic downturn.
Diana Mousina is the Deputy Chief Economist of AMP Capital, this article was first published at the AMP Insights Hub